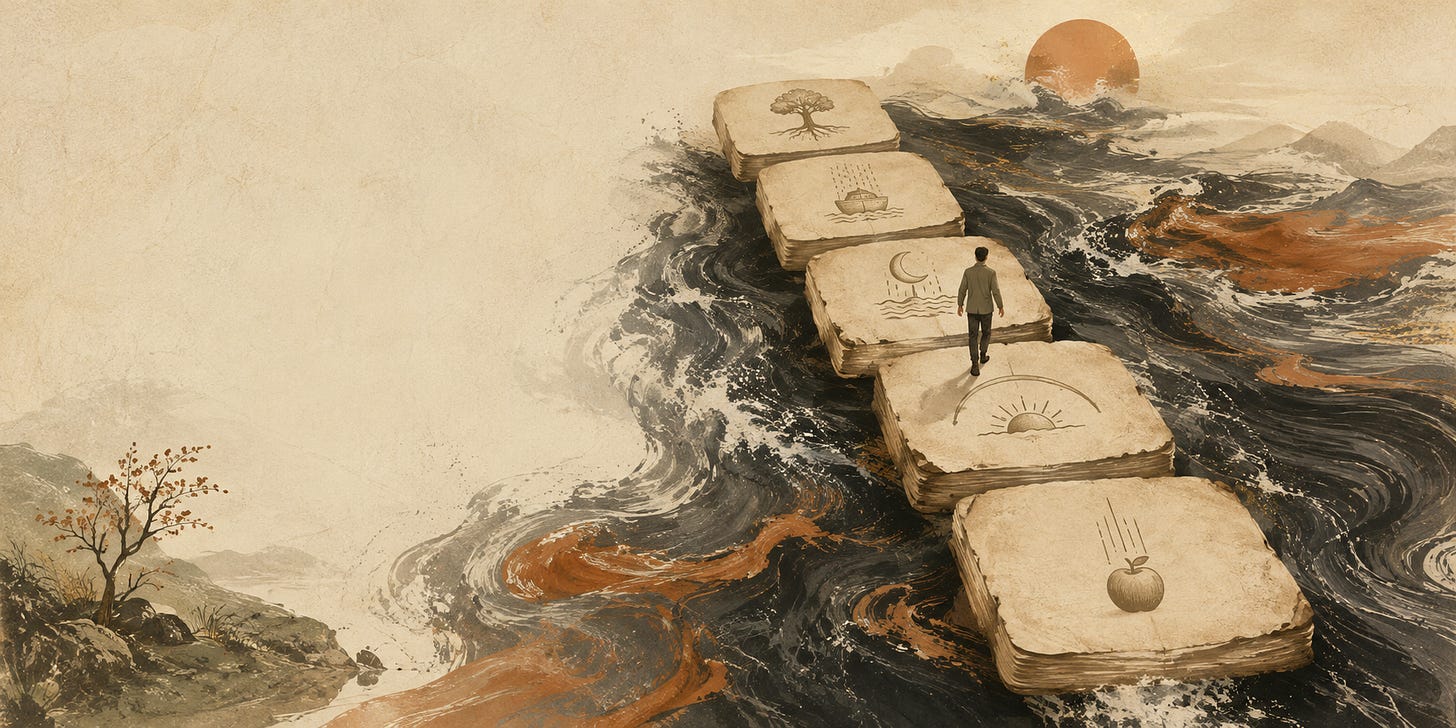
Here is what the last week of August 2026 looks like.
Nvidia jumped 9.3% the day after earnings and the Nasdaq rose 1.5%. The Dow slipped. It was a day when one sector went up and everything else sat still. The S&P 500 sits near an all time high at roughly 20 times expected earnings. AI infrastructure stocks are up 48% this year while the index as a whole is up 9%. In Seoul, the KOSPI fell more than 4% intraday on August 25, then closed higher, while foreign investors sold for a third straight day. The Fed is holding its policy rate near 3.6%, and markets price about a 30% chance of a hike. Core PCE inflation is 3.3%, a long way from the 2% target. The real yield on 30 year inflation protected Treasuries has moved above 3%, the highest since 2008. The Iran war and tanker attacks pushed Brent up 7.5% in a week to more than $88. Gold touched $4,400 an ounce. And today Kevin Warsh, the new Fed chair, gives his first Jackson Hole speech.
Stocks at record highs, inflation sticky, real rates at a generational high, oil hostage to geopolitics, and every screen tuned to a new central banker’s first words. In a week like this, reading one more piece of fresh analysis helps less than rereading a few old sentences. Most of what the survivors of this business left behind was written in exactly this kind of moment.
One. Interest rates act on asset prices the way gravity acts on the apple
Warren Buffett said this at Sun Valley in 1999. High rates pull every asset price down; low rates loosen the grip. What matters is not the nominal rate but the real one. A 3% real yield on the 30 year is a number nobody has seen since 2008. The earnings yield on the S&P 500, the inverse of a 20 multiple, is about 5%. That leaves an equity premium of roughly two percentage points in real terms for taking stock market risk. To beat that gravity, earnings have to keep growing faster than expected. Like Nvidia’s. The problem is that not every company is Nvidia. That is why the rally keeps narrowing to one sector.
Two. Bull markets are born on pessimism, grow on skepticism, mature on optimism and die on euphoria
This is widely attributed to Sir John Templeton. The exact source has never been pinned down, but the sentence fits his philosophy. Its value is that it forces you to ask which of the four stages you are in. Korean retail and institutions bought the KOSPI plunge on sight. AI infrastructure has returned five times the broad market. Hyperscaler bond issuance makes up 16% to 23% of everything sold in the US investment grade, high yield and leveraged loan markets this year. This is not pessimism. Skepticism is behind us too. Most people would place us somewhere between optimism and euphoria. The signature of euphoria is the feeling that risk has gone away. It has not gone anywhere. It is already printed on the price tag, in the form of a 3% real yield.
Three. Earnings don’t move the overall market. The Federal Reserve does. Watch the central banks and watch the movement of liquidity
Stanley Druckenmiller said this in an interview in the early 1990s. It explains why today’s Jackson Hole speech matters more than Nvidia’s quarter. Nvidia is one stock. One sentence from Chairman Warsh changes the direction of the 3.6% gravity that acts on all of them. The market is split 30 to 70 between a hike and a hold. Which way that number tilts decides where asset prices go next quarter. During earnings season it is easy to drown in company news. That is exactly when this sentence belongs on the wall above your desk.
Four. Predicting rain doesn’t count. Building arks does
Buffett wrote this in his 2001 shareholder letter, explaining insurance losses after September 11. Nobody is good at predicting when the Iran war ends, whether another tanker gets hit, or whether new semiconductor tariffs land. What you can do instead of predicting is calculate now what happens to your portfolio if oil goes to $100. Gold at $4,400 is a sign that some people are already building arks.
Five. Far more money has been lost by investors preparing for corrections than has been lost in corrections themselves
Peter Lynch. After the first four sentences you may want to sell everything. That is why this one has to come last. August 25 in Seoul is the example: down 4% at midday, up at the close. Whoever sold into the fear regretted it by dinner. High real rates and rich valuations are not a signal to leave the market. They are a signal to go back and check what you own and what you paid for it. Companies with real earnings, low debt, and balance sheets that hold up at 3.6%. That is usually all a maxim asks of you. Not a dramatic move. A checkup.
In one line
Rates are gravity, and gravity is the strongest it has been in a generation. The bull market is somewhere between optimism and euphoria. What moves the market today is Jackson Hole, not earnings. Don’t predict, prepare. But preparing does not mean leaving. Compress the five sentences into one and you get this: the way to survive an expensive market is not to be right. It is to still be there.
The story of money. Every story of capital leads here.
Sources and dates
- Market data (S&P 500 +0.68%, Nasdaq +1.51%, Nvidia +9.3%, core PCE 3.3%, Warsh Jackson Hole speech): TheStreet, August 27, 2026
- 30 year TIPS real yield above 3% (highest since 2008), CPI 3.4%, Brent $88.46 (+7.5%), gold $4,406, S&P 500 at about 20x forward earnings, about 30% odds of a September hike: FXCM Global Macro and Markets Briefing, August 17, 2026
- Fed funds 3.625% forecast, July payrolls and retail sales negative, hold through 2026: MUFG Research, August 20, 2026
- AI infrastructure +48% vs S&P 500 +9%, hyperscaler share of issuance 16 to 23%: Goldman Sachs Asset Management, US Market Pulse, August 2026
- KOSPI close 6,742.74 (intraday low 6,408.82), third day of foreign selling: Infostock Daily, August 25, 2026
- Buffett on gravity: Sun Valley speech, July 1999, published in Fortune, November 1999
- Buffett on arks: Berkshire Hathaway 2001 shareholder letter, February 2002
- Druckenmiller: Jack Schwager, The New Market Wizards, 1992
- Templeton: source unverified, widely quoted
- Lynch: repeated in columns and talks in the 1990s, first appearance unverified